
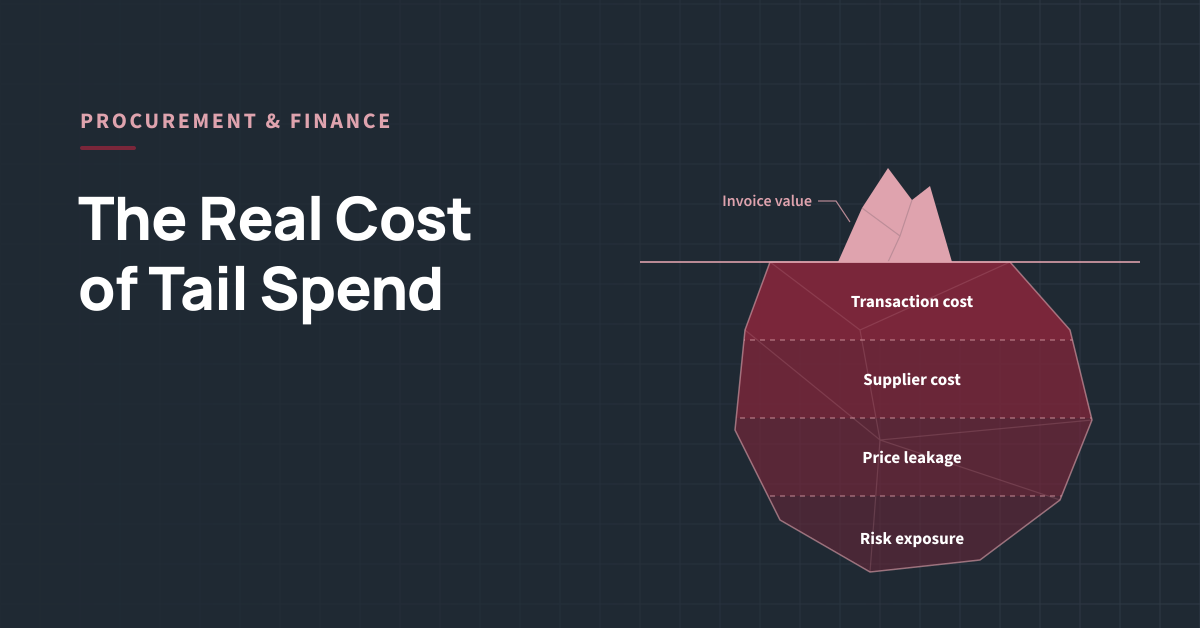
Tail spend is easy to underestimate. Each purchase is small, so it rarely gets attention in budget reviews or sourcing plans. But the invoice value is only the visible part. Behind every small purchase sits a process that costs money to run, a supplier that costs money to maintain, a price that nobody negotiated, and a risk that nobody checked.
This guide breaks the real cost of tail spend into four layers, shows who in procurement, finance and accounts payable owns each one, sets out the controls that work, and gives you a simple worksheet to build a business case with your own numbers.
Why Does Low-Value Spend Carry a High Total Cost?
Short answer
Tail spend costs more than its invoice value because every purchase, however small, triggers the same process: a request, a purchase order, an invoice, a payment and often a new supplier record. Add unnegotiated prices and unchecked supplier risk, and the total cost of the tail can be far higher than the spend itself.
Key Takeaways
-
- The cost of tail spend has four layers: transaction cost, supplier cost, price leakage, and risk and compliance exposure.
-
- Process and supplier costs are fixed per transaction or per supplier, so they weigh most heavily on low-value purchases.
-
- Procurement, finance and accounts payable each see part of the cost. None of them sees all of it alone.
-
- Simple controls, such as P-card policy, approval thresholds, no-PO-no-pay and preferred supplier lists, address most of the leakage.
-
- Build the business case from your own data, using the formulas in this guide.
The Four Layers of Tail Spend Cost
Think of tail spend as an iceberg. The invoice value sits above the waterline. Four layers of cost sit below it, and each one is visible to a different team.
Cost Layer 1: Transaction Cost
Every purchase goes through a process, and that process has a cost regardless of what is bought. A typical purchase-to-pay cycle includes:
-
- Requisition: the requester finds a supplier, gets a quote and raises a request.
-
- Approval: one or more managers review and approve it.
-
- Purchase order: procurement or the system creates and sends a PO.
-
- Invoice processing: AP receives, checks, matches and resolves any queries.
-
- Payment: finance schedules and makes the payment, then reconciles it.
The cost of this cycle is roughly the same for a small purchase as for a large one. That makes it a much bigger share of the value of a tail purchase. Many organisations track this as cost per purchase order. If you do not yet know yours, estimate it from the time each step takes and the cost of the people and systems involved.
Cost Layer 2: Supplier Cost
Each new supplier adds work that continues long after the first purchase. Procurement or AP must set up the supplier record, verify bank details, collect tax and insurance documents, and run any due diligence checks your policy requires. After that, the record needs maintaining: contact changes, document renewals, periodic risk reviews and eventually deactivation.
In the tail, many suppliers are used only once or twice. The full cost of onboarding and maintaining each one is spread across very little spend. A long list of rarely used suppliers is one of the clearest signs that tail spend is costing more than it should.
Cost Layer 3: Price Leakage
Price leakage is the difference between what you paid and what you could have paid through a better channel. In the tail it comes from three sources:
-
- No negotiation. Small purchases are bought at list price because no one has time to negotiate.
-
- No consolidation. The same items are bought from many suppliers, so no single supplier sees enough volume to offer better terms.
-
- Off-contract buying. Agreed prices exist, but buyers go elsewhere because the contracted route is slow or hard to find.
Price leakage is usually the easiest layer to quantify, because it can be measured by comparing prices paid for similar items. Routing recurring purchases to catalogues and preferred suppliers, as described in our 6-step tail spend strategy framework, addresses most of it.
Cost Layer 4: Risk and Compliance Exposure
This layer is the hardest to put a number on, but it can be the most expensive. Tail suppliers often skip the checks applied to strategic suppliers. That creates exposure to:
-
- Payments to suppliers that fail sanctions, anti-bribery or modern slavery checks
-
- Invoice fraud and duplicate payments, which are harder to spot across many small suppliers
-
- Data protection breaches when small suppliers handle personal or sensitive data
-
- Missing insurance, safety or quality certificates for suppliers working on site
-
- Audit findings and control failures when spend bypasses policy
You do not need to price every risk to make the case. Showing how many tail suppliers have not been through your standard checks is often enough to get leadership attention.
Signs Your Tail Spend Is Costing Too Much
You can spot most hidden tail costs before running a full analysis. Look for these warning signs in your own data and processes:
-
- A long supplier list. Many suppliers have received only one or two payments in the last year.
-
- Many invoices without a PO. AP regularly chases approvals after the goods or services have been delivered.
-
- The same items from many suppliers. Common categories, such as IT accessories or office supplies, appear under several supplier names.
-
- Heavy expense and card use. Business purchases routinely go through personal expense claims, or card spend is rising with little review.
-
- Slow, frustrating requests. Buyers complain that small purchases take too long, which usually means they are finding workarounds.
-
- Gaps in supplier checks. No one can say with confidence how many active tail suppliers have been through due diligence.
If three or more of these sound familiar, the hidden cost of your tail is likely to be significant, and the business case below is worth building.
Who Owns the Tail? A Shared RACI
Tail spend falls between teams. Procurement owns suppliers and channels, finance owns budgets and cards, and AP owns invoices and payments. A shared RACI makes ownership clear. Adapt the one below to your structure.
R = Responsible, A = Accountable, C = Consulted, I = Informed.
Controls That Work
Good controls reduce cost without slowing buyers down. If a control makes the approved route harder than the workaround, people will use the workaround. These four controls address most tail spend leakage:
Technology and services can make these controls easier to run at scale. Tail spend software builds them into guided buying flows, while managed services and outsourcing add buying capacity for the requests your team cannot reach.
Building the Business Case
A strong business case uses your own numbers, not industry averages. Use the worksheet below to estimate each cost layer. Fill in the “Your figure” column from your spend data and finance records.
Then calculate each layer:
Add the three figures for the annual cost of the tail beyond its invoice value. To estimate the opportunity, model realistic changes: fewer transactions through P-cards and catalogues, fewer active suppliers through consolidation, and lower prices on addressable spend. Describe risk exposure separately, using the number of unchecked suppliers and any past incidents or audit findings.
Present the case jointly from procurement and finance. A shared case is more credible, and it commits both teams to the controls that deliver the savings.
Next step
See where your organisation stands. The Tail Spend Management Assessor asks four quick questions and points you to the management approach that fits your profile.
Frequently Asked Questions
What is the true cost of tail spend?
The true cost of tail spend is its invoice value plus the hidden costs behind it: processing each transaction, onboarding and maintaining suppliers, paying unnegotiated prices, and carrying unchecked supplier risk. For low-value purchases, these hidden costs can be a large share of the total.
How do I calculate cost per purchase order?
Add up the time each step of the purchase-to-pay process takes, from request to payment, and multiply it by the cost of the people involved. Add a share of system and overhead costs, then divide by the number of purchase orders processed in the same period.
Who should own tail spend: procurement or finance?
Both. Procurement owns suppliers, channels and sourcing, while finance owns budgets, approvals and card programmes, and accounts payable owns invoices and payments. A shared RACI and joint KPIs keep everyone accountable.
Should we use P-cards for tail spend?
P-cards work well for low-value, low-risk purchases because they remove the cost of a PO and invoice. They need clear limits, blocked merchant categories and regular reconciliation, so card spend stays visible and within policy.